Our grandparents handled money differently. They saved what they could, made things last, and thought twice before spending their hard-earned cash. Many of the habits they practiced weren’t particularly exciting, but they helped families make ends meet without constantly buying more.
Of course, things were different back then. Housing, groceries, and everyday expenses have changed considerably, and not everyone had the same financial opportunities. Still, there’s something to be said for the way previous generations approached saving, spending, and making the most of what they already had.
Looking back, some of those old-fashioned money habits were surprisingly smart. Here are 12 things our grandparents did with money that are still worth considering today.
They Grew Some of Their Own Food
Many grandparents kept vegetable gardens filled with tomatoes, beans, potatoes, and other foods their families regularly ate. Growing produce at home helped stretch the grocery budget, particularly when they saved seeds, composted, and preserved extra harvests. Gardening isn’t always cheaper once supplies and time are considered, but a productive garden can help reduce food costs.
They Lived Within Their Means, Even When They Earned More
Getting a raise didn’t automatically mean buying a newer car, moving into a bigger house, or upgrading everything they owned. Many families continued living much as they had before and put the extra money toward savings, bills, or paying down debt. They also understood the difference between needing something and simply wanting it, which helped them avoid spending money just because they could.
They Budgeted With Cash and Spent Only What They Had
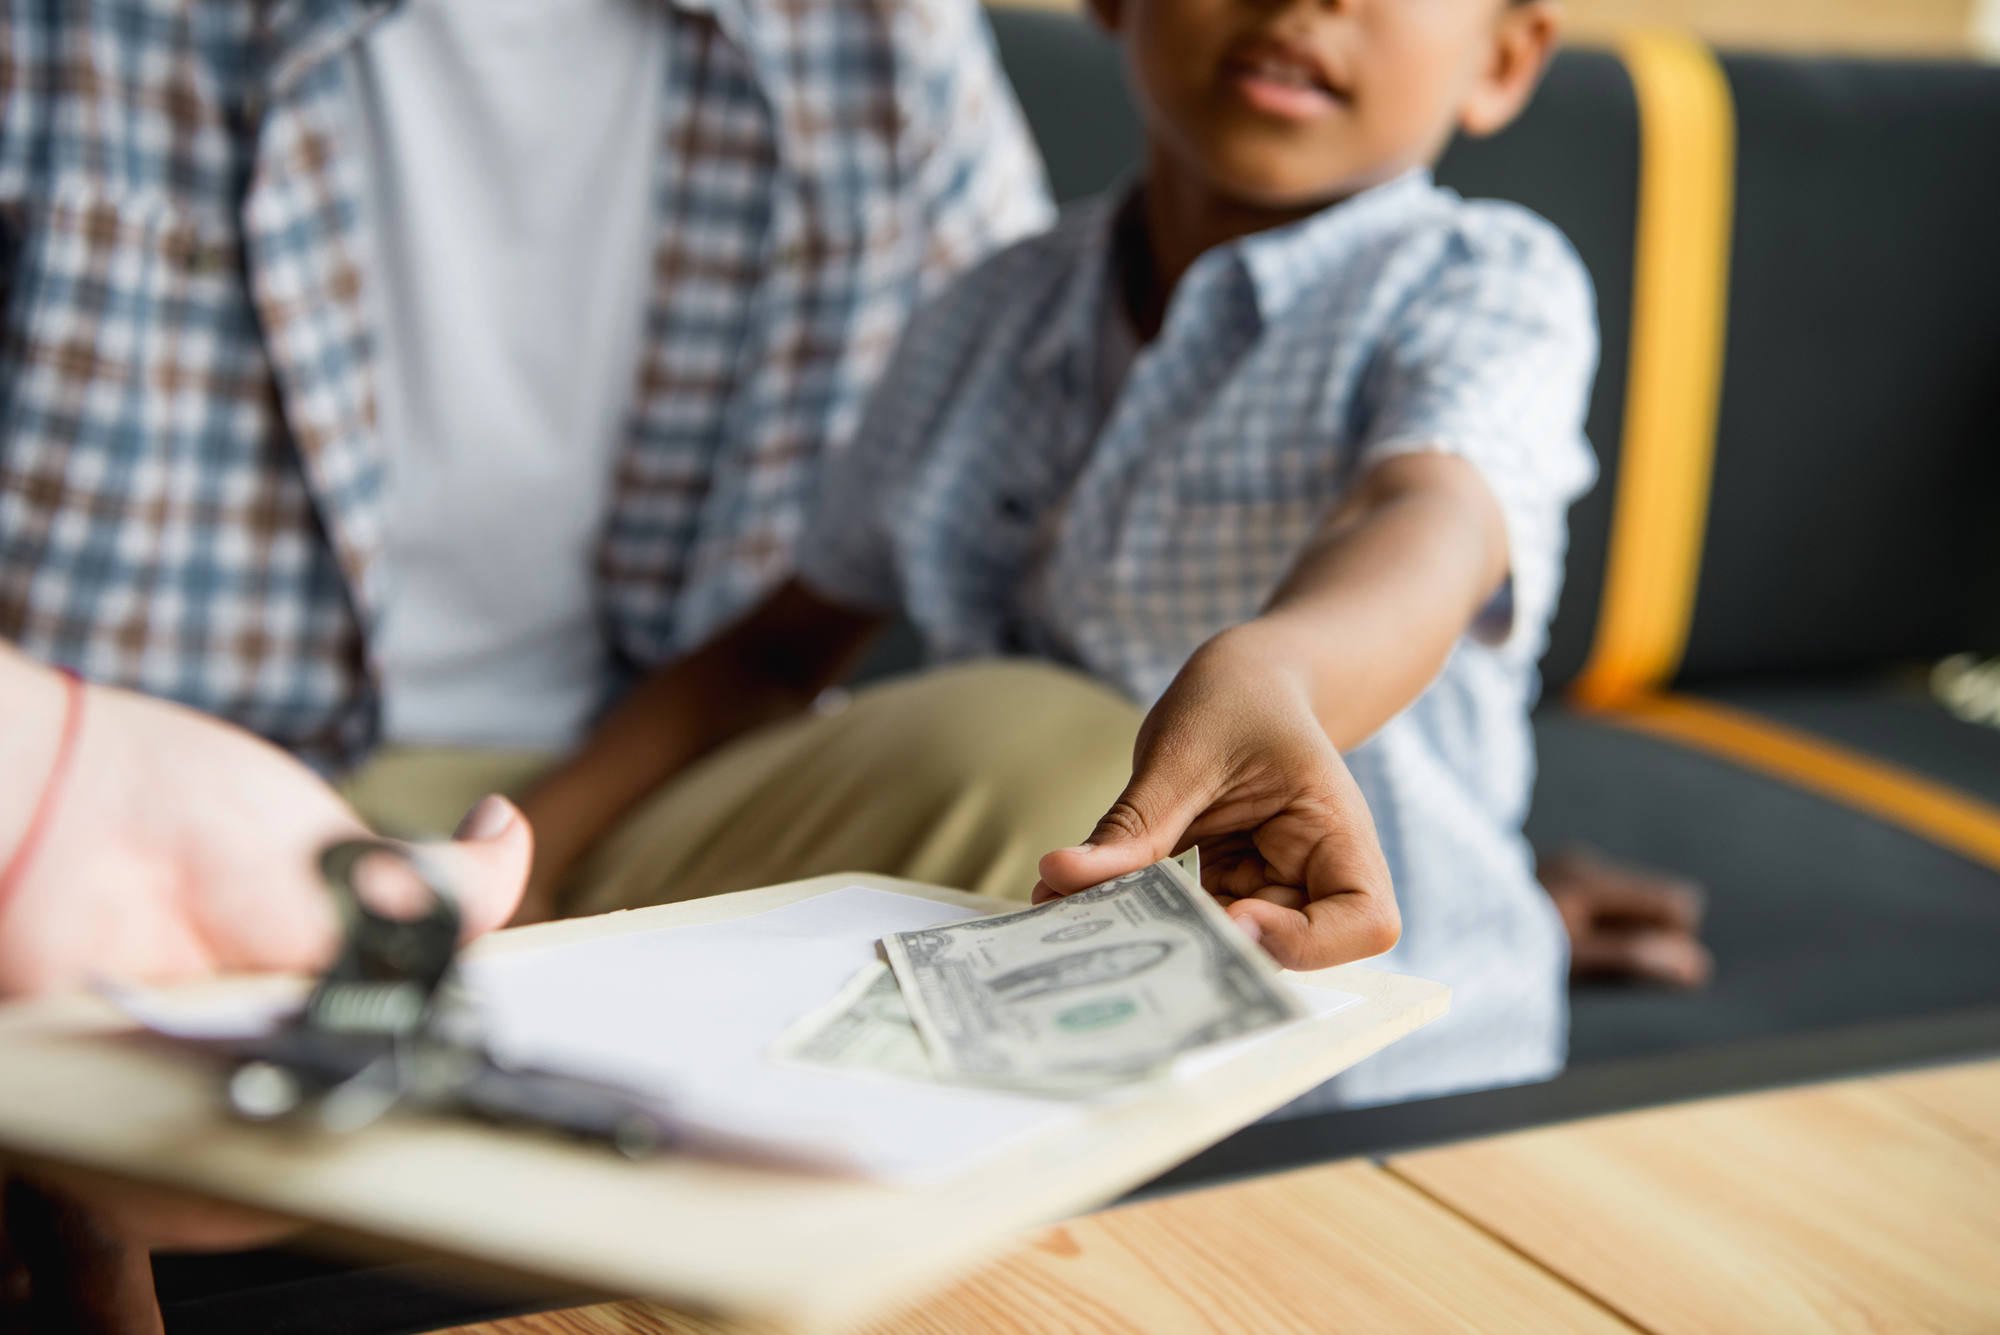
Before budgeting apps and online banking, many households divided their money into envelopes labeled groceries, bills, clothing, and other expenses. Once an envelope was empty, that was usually the end of spending in that category until more money came in. Paying with cash also helped them avoid borrowing money for everyday purchases and made it easier to see exactly how much they were spending.
They Saved Money Whenever They Could
A jar of coins on the kitchen counter was a familiar sight in many households, and every bit of leftover change went into it. When unexpected money came their way, whether from a bonus, gift, or tax refund, they often saved some of it instead of immediately spending it. Those small amounts could eventually add up to money for emergencies, household expenses, or something special for the family.
They Bought Quality and Made Things Last
Our grandparents often preferred a sturdy pair of shoes, reliable furniture, or well-made kitchen equipment over cheaper items that needed frequent replacing. When something broke, they tried to repair it rather than immediately buying a replacement. This approach helped them get more use out of their belongings while avoiding unnecessary purchases.
They Taught Their Children About Money Early
Many grandparents involved children in everyday money decisions, whether that meant counting change, saving allowance money, or explaining why the family couldn’t afford something. These small lessons helped children understand that money was limited and that saving required patience. Teaching kids to budget, compare prices, and make thoughtful purchases can build useful financial habits long before they start earning their own money.
Related: 15 Habits That Make Keeping a Clean Home Feel Less Like Work
They Planned Their Meals and Cooked at Home
Eating out was often reserved for birthdays, anniversaries, or an occasional family treat rather than something that happened several times a week. Our grandparents planned meals around what was already in the pantry, made grocery lists, and looked for sales before heading to the store. Cooking at home and using leftovers helped them stretch their food budgets without constantly spending money on takeout.
They Saved Up for Big Purchases Instead of Going Into Debt
Buying something expensive often meant saving for it, comparing prices, and waiting until there was enough money set aside. That waiting period gave them time to decide whether they really needed the item or could continue using what they already owned. By avoiding unnecessary borrowing and paying off credit balances when possible, they also avoided interest charges that could make purchases much more expensive.
Related: 15 Things You May Regret Charging to Your Credit Card
They Worked Toward Paying Off Their Homes
For many homeowners, paying off the mortgage was a major financial milestone and something worth celebrating. Owning a home without a monthly mortgage payment could make retirement easier and free up money for other expenses. Paying off a mortgage early isn’t always the best financial decision for everyone, but reducing housing debt can provide valuable peace of mind.
They Traded Skills and Favors With Neighbors
Not every household expense required money to change hands. Neighbors often helped one another with repairs, gardening, childcare, and other tasks, exchanging skills or favors instead of paying someone for every little job. Building those relationships could save money while creating a community where people could count on one another when they needed help.
They Kept Track of Every Dollar
Before banking apps made it possible to check your balance in seconds, many households kept handwritten records of their income and expenses. Writing down purchases made it easier to spot where money was going and whether there was enough left to cover upcoming bills. You don’t need a paper ledger today, but regularly reviewing your spending can help you catch unnecessary expenses before they become habits.
They Focused on Long-Term Investments
Rather than constantly chasing the next opportunity to make quick money, some grandparents built wealth through steady saving, retirement accounts, property, or long-term investments. Their approach often centered on patience and letting money grow over many years. Investing consistently in diversified, low-cost funds is one modern way to follow that principle without relying on risky speculation.